
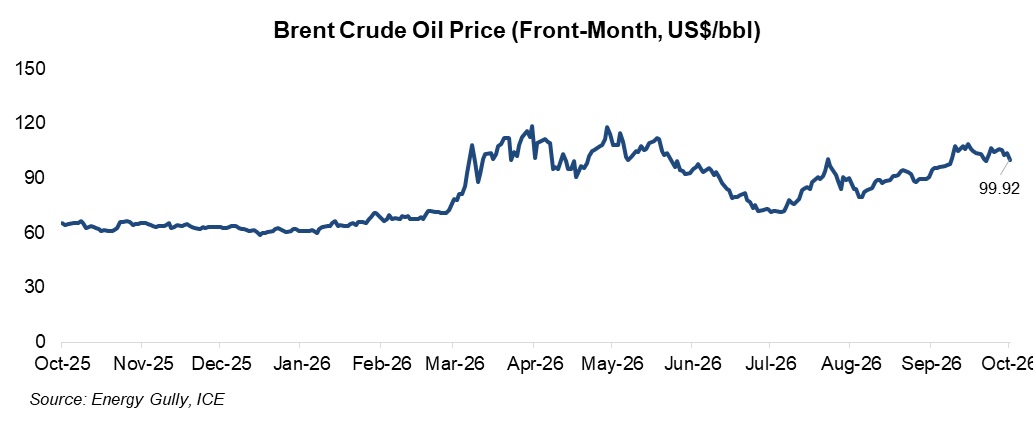
Brent crude oil price have been rising again over the last two days amid no concrete signals yet of ending the Middle East conflict. This is despite the fact that physical crude oil movement through the Strait of Hormuz has picked up substantially over the recent days. As per KPLER’s data, crude oil exports from Saudi Arabia, the UAE, Iraq, Oman, Qatar, Kuwait and Iran averaged 16.33 million barrels per day (MMBD) in September, only about 3.2 MMBD less than the 19.51 MMBD recorded in February this year. This means that oil exports from the region have now recovered to around 84% of the pre-conflict level.
Nevertheless, flow of crude is just one part of the broader energy security story as the flow of oil products still remained constrained, keeping the flat price high. Moreover, the market wants to see sustained crude flows before lowering its price expectations.
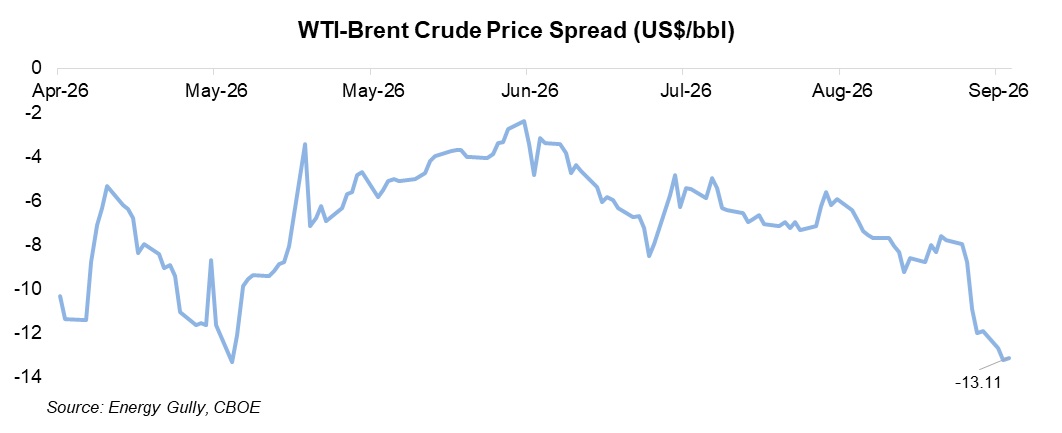
 Brent-WTI spread widens: The price discount of WTI crude over Brent crude price has deepened further to US$13.1/bbl on expectations of diesel ban by the US which could trim domestic refinery runs and thus weigh on crude demand. Meanwhile, high VLCC freight market is also making sure that price of WTI crude adjust downward vis-à-vis Brent crude price to keep arbitrage open for US crude exports.
As of now, the US administration has not put a ban on diesel exports though there are discussions happening around several alternatives including a blanket export ban, voluntary export limits by refiners, or expanding access to tax-exempt diesel. However, US energy officials also have a view that a blanket ban could lead to diesel supply surplus on the US Gulf Coast, and thus make refiners cut runs. This could reduce gasoline supplies and push its price higher. The US administration is also reported to have urged the European Union to release emergency diesel stocks to help ease prices.
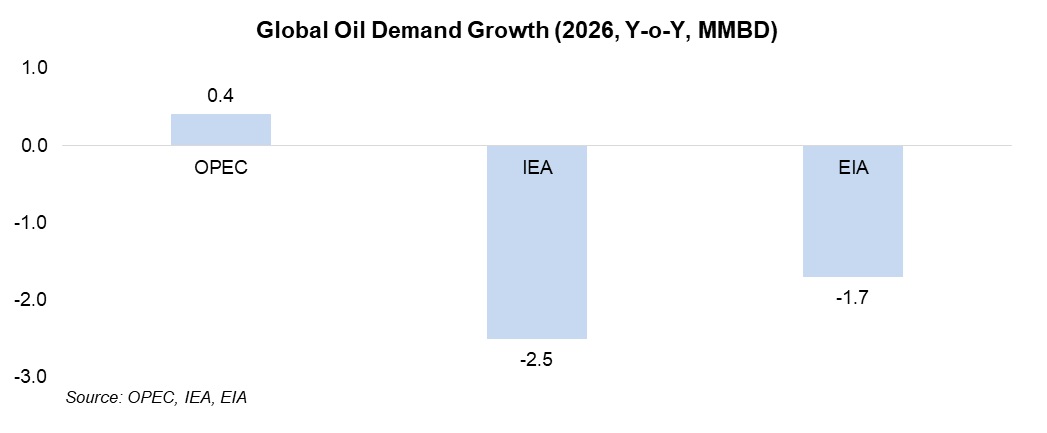
Demand Outlook by IEA, EIA and OPEC: There is still no clear direction when it comes to oil demand outlook by major agencies. Among the three, OPEC is the most bullish as it still expects that the global oil demand would grow by 0.4 MMBD, y-o-y, in 2026. Meanwhile, the IEA and EIA are expecting demand contraction of -2.5 MMBD and -1.7 MMBD as high fuel prices hit demand through several channels including voluntary curtailment, fuel switching etc.
 Signals to watch in October:
- OPEC+ member meeting: The seven OPEC+ countries will have their next virtual meeting on October 4, 2026. Member countries are likely to keep their oil production targets steady for November as most are still pumping well below their output targets. The market is also looking beyond the immediate production decision toward 2027 production quotas. A major issue will be how OPEC+ incorporates members’ revised production capacities into future quotas.
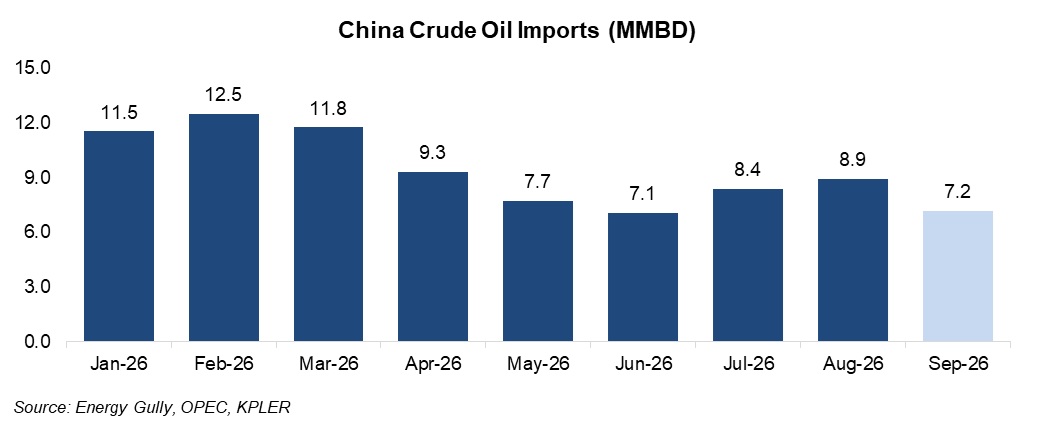
- China’s oil demand: There is a lot of interest around China’s crude oil imports strategy because if it slows down its purchase, other big buyers (such as India) could easily secure supply from the spot market without pushing-up the premiums strongly. After cutting its imports in May and June, China had started securing more as its imports averaged 8.7 MMBD over July-August, compared to 7.4 MMBD over May-June. However, preliminary data for September suggest that its imports have again cooled to around 7.2 MMBD. With Brent price close to US$100/bbl, China’s refiners may decide to keep a lid on their buying. Nevertheless, China’s crude import strategy is worth tracking over the coming months.
- Diesel margins: Global diesel cracks remain elevated because of tight inventory, seasonal demand and refinery disruptions in Russia. The ultra-low sulfur diesel futures crack spread in the US jumped to a record closing high of around US$118/bbl on September 16. Diesel margins in Asia and Europe are also near record level and refiners across the regions are keeping their run rates high to capture these robust margins. The trajectory of diesel margins in October is worth watching: will record high diesel margins come off or will the US impose new export restrictions which could further tighten the international diesel market?